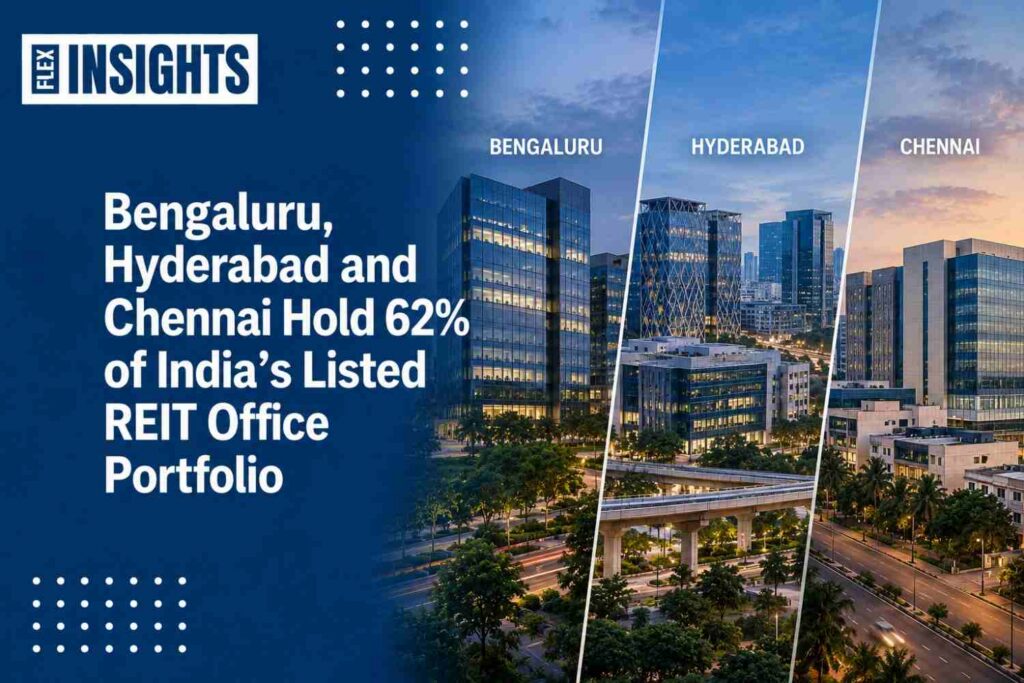
Bengaluru, Hyderabad and Chennai together account for 62% of office space owned by India’s listed REITs, highlighting the growing institutionalisation of commercial real estate. Listed REITs held 167 million sq ft across eight major cities as of June 2026, with Bengaluru recording the highest REIT penetration.
India’s listed Real Estate Investment Trusts are becoming an increasingly important force in the country’s office market, with Bengaluru, Hyderabad and Chennai emerging as the clear centres of institutional ownership. Together, the three cities accounted for 103.5 million sq ft, or about 62%, of the 167 million sq ft of office space held by listed REITs across India’s eight major cities as of June 2026.
The findings come from the Building Viksit Bharat: Real Estate as a Catalyst for Growth report by Assocham and Knight Frank India. The report was unveiled at an Assocham real estate conference and highlighted the expanding role of REITs in aggregating assets, monetising mature properties and recycling capital into new investments.
India currently has five listed REITs backed by office assets: Brookfield India Real Estate Trust, Embassy Office Parks REIT, Mindspace Business Parks REIT, Knowledge Realty Trust and Bagmane Prime Office.
Bengaluru Leads REIT Penetration
Bengaluru remains the strongest REIT market among India’s major office hubs. The city had 67.6 million sq ft of REIT-backed office stock, representing 27% of its total workspace inventory.
Embassy Office Parks remains the largest REIT platform in Bengaluru, while Bagmane’s portfolio has further increased the share of listed institutional ownership in the city. The scale of REIT participation underlines Bengaluru’s importance to India’s Grade A office ecosystem and its appeal to long-term institutional capital.
Hyderabad ranked second, with 26.2 million sq ft of REIT-backed office space representing 20% of its total office inventory. Knowledge Realty Trust and Mindspace have played a key role in supporting institutional ownership in the market.
Mumbai followed with 24.6 million sq ft of REIT stock, equal to 14% of its office inventory. Delhi-NCR and Pune each accounted for 11% of REIT share, while Chennai and Kolkata stood at 10%.
REITs Strengthen Capital Recycling
The wider market remains significantly larger than the REIT segment. India’s eight major cities had a total office stock of 1,054.6 million sq ft as of June 2026, with listed REITs accounting for roughly 16% of the overall portfolio.
Knight Frank India Chairman and Managing Director Shishir Baijal said the expansion of listed REITs has strengthened the “exit and capital-recycling mechanism” available to institutional real estate investors. He noted that stabilised assets can be aggregated into listed portfolios, giving a broader investor base access to institutional-grade real estate.
For developers, landlords and flexible workspace operators, deeper institutional ownership could support greater transparency, professional asset management and investment in high-quality commercial properties.
Institutionalisation Moves Beyond Offices
REIT-led institutionalisation is also spreading beyond the traditional office sector. The report noted that India’s operational retail REIT portfolio stood at 11 million sq ft as of June 2026. Meanwhile, the warehousing InvIT portfolio reached 44.2 million sq ft.
Roads and fibre continue to dominate the broader InvIT asset base, but warehousing is becoming an increasingly important component as logistics and supply chain infrastructure expands.
Assocham Secretary General Saurabh Sanyal said real estate is “no longer just a beneficiary of economic growth” but is becoming a critical growth enabler for India. The growing footprint of REITs and InvITs could therefore play a wider role in financing the offices, retail assets and infrastructure needed to support India’s Viksit Bharat ambitions.



Leave a Comment
You must be logged in to post a comment.