
India’s mid-market businesses are outgrowing traditional office infrastructure. Discover how enterprise-grade workspaces provide the flexibility, technology, security and professional environment needed to scale faster.
For decades, premium office infrastructure was largely associated with multinational corporations and large enterprises. High-quality workplaces with advanced technology, professional facility management, robust security and seamless operational support were often viewed as investments that only organisations with significant real-estate budgets could justify.
That distinction is steadily disappearing.
India’s mid-market businesses are expanding rapidly. They are entering new cities, building regional teams, hiring from wider talent pools and serving customers across multiple markets. Their ambitions increasingly resemble those of much larger enterprises, but their workplace infrastructure does not always evolve at the same pace.
For these businesses, the conversation around office space is no longer simply about square footage. It is about whether the workplace can support the speed, consistency and professionalism required for the next stage of growth.
Mid-Market Ambition Has Outgrown Mid-Market Infrastructure
The evolution of India’s flexible workspace market reflects this broader change.
According to Knight Frank India’s Flex Space Occupier Intelligence 2026, flex-space absorption increased from 2.2 million sq. ft. in 2017 to 18.6 million sq. ft. in 2025, an 8.4-fold increase. Flex spaces accounted for 21% of total office absorption in 2025, compared with just 5% eight years earlier. GCCs accounted for 52% of flex demand, demonstrating how deeply flexible workspace has entered mainstream enterprise real-estate strategy.
But this shift is not limited to large corporations.
Colliers found that around 45% of surveyed mid-sized companies were already carrying out core business operations from flexible workspaces, compared with 35% of large companies. This is an important indicator of how the market is changing. Mid-sized organisations are not simply using flex as temporary overflow space; for many, it is becoming part of the infrastructure through which the core business operates.
Operator-level data provides another useful signal. Industry data as of March 2026 shows SMEs representing roughly 25% of client distribution at a major national flex-space operator, within an overall client base of approximately 3,500 customers. While this is an operator-level measure rather than a market-wide estimate, it reinforces the growing participation of smaller and mid-sized businesses in professionally managed flexible workspaces.
The underlying reason is straightforward: business ambition is scaling faster than the willingness, or the need, to take on traditional real-estate complexity.
Enterprise-Grade Without Enterprise-Level Real Estate Commitments
A growing company may need enterprise-quality infrastructure, but it does not necessarily need to behave like a large corporate occupier from day one.
Setting up a conventional office can involve property search, lease negotiations, deposits, interior design, fit-outs, connectivity, security, maintenance contracts and facility-management teams. Each of these requires management attention and capital before the workplace is fully operational.
A professionally managed workspace changes that equation.
Businesses can access ready infrastructure, private offices, meeting facilities, technology, security and operational support without independently building every component themselves. This allows leadership teams to direct more attention towards product development, customer acquisition, hiring and market expansion.
The advantage becomes even more relevant when a company enters a new city.
Mid-market businesses often expand in response to a customer requirement, a new regional opportunity, a project mandate or access to talent. At this stage, visibility on future headcount may still be limited. Committing immediately to a long conventional lease can therefore create unnecessary rigidity.
Flexible workspaces allow companies to establish a professional presence quickly, begin with the capacity they require today and adjust as the business develops.
This does not mean conventional offices are becoming irrelevant. For large, stable teams with highly customised infrastructure requirements, a traditional lease may continue to make commercial sense. The value of flexible workspace lies in giving growing businesses another option, particularly when speed, uncertainty or regional expansion are part of the equation.
Consistency, Talent and Speed Are the New Competitive Advantages
As mid-market companies expand into multiple cities, a less visible challenge begins to emerge: maintaining consistency.
Different offices can quickly develop different technology standards, security protocols, employee experiences and service levels. Managing several landlords, fit-out vendors and facility teams also adds operational complexity.
A standardised flexible-workspace network can help reduce this fragmentation.
Operator data from the same period shows 48% of clients at a major national flex-space operator using more than one centre, offering a useful indication of the growing importance of multi-location workspace requirements. For expanding businesses, having access to professionally managed offices across locations can make it easier to provide employees and clients with a more consistent experience.
Talent is another part of the equation.
India’s skilled workforce is increasingly distributed across Tier II cities and emerging business centres. Growing companies no longer need to build every team around a handful of metropolitan locations. But professionals in regional markets also expect workplaces that offer strong connectivity, professional environments, meeting infrastructure and a workplace experience comparable with that of larger organisations.
This is where the definition of a “premium office” needs to change.
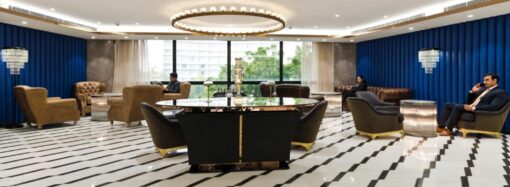
For a mid-sized business, enterprise-grade infrastructure should not necessarily mean marble lobbies or expensive interiors. It should mean reliability: secure access, dependable technology, professional meeting environments, operational support and a workplace that reflects the company well to employees, customers and partners.
Speed is equally important.
A market opportunity can emerge faster than a conventional office can be established. A new customer may require local support. A sales team may need to enter a city. A project may require immediate mobilisation. A company may identify a new talent market that it wants to test before making a larger commitment.
In such situations, workplace agility becomes a business capability rather than merely a real-estate preference.
This direction is likely to strengthen further. Colliers found that more than 80% of surveyed occupiers planned to expand through flexible workspaces over the following three to five years, while around 60% expected flex to account for at least 20% of their office portfolio.
The implication for India’s mid-market businesses is significant. Access to enterprise-grade infrastructure no longer needs to follow enterprise-scale real-estate commitments.
As these companies expand beyond their home markets, compete for talent and build more distributed operations, their workplaces will increasingly need to offer the same reliability and professionalism traditionally associated with much larger organisations.
Enterprise-grade workspace should therefore not be viewed simply as a premium amenity. For a growing business, it can become part of the infrastructure that enables expansion.
The next generation of Indian mid-market companies will be defined not only by the markets they enter or the customers they acquire, but also by how effectively their operating infrastructure keeps pace with their ambition.