
India’s office market is seeing a strong shift toward premium and tech-enabled workspaces. A CBRE survey shows that 40% of occupiers are concerned about the availability of quality office space through 2028. With GCCs driving leasing, demand is favouring Grade-A assets, while older properties could face rising vacancies and competitive pressure.
India’s commercial office market is entering a new phase where the quality and location of workspace are becoming as important as the availability of space itself. According to a recent CBRE survey, 40% of office occupiers are concerned about securing high-quality, well-located office space through 2028.
The concern comes at a time when leasing activity remains exceptionally strong. India recorded around 45.5 million sq ft of office leasing in the first half of 2026, indicating that occupier demand continues to expand despite broader economic uncertainties. However, much of this demand is increasingly concentrated in modern, investment-grade properties.
GCCs Lead the Flight to Quality
Global Capability Centres (GCCs) are emerging as a major force behind this shift. They accounted for 43% of India’s office leasing activity in H1 2026, with many global occupiers looking beyond basic workspace requirements.
For these companies, office locations need to support talent attraction, employee experience and business continuity. This is increasing demand for buildings with strong digital infrastructure, sustainability credentials, modern amenities and convenient access to transport networks.
Established business districts are therefore gaining an advantage over peripheral locations. Nearly half of the occupiers surveyed prefer core locations, reflecting the importance of connectivity and proximity to established commercial ecosystems.
Grade-A Assets Stand to Gain
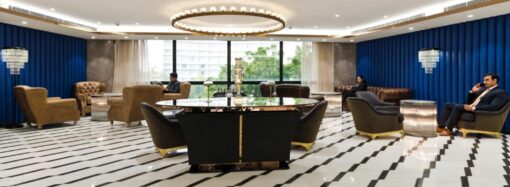
The concentration of demand is creating a two-speed commercial real estate market. Modern Grade-A properties held by major developers and REITs are positioned to benefit from the flight-to-quality trend. Stronger tenant demand can support higher rentals, healthier occupancy and more stable cash flows for these assets.
For landlords, the changing preferences also create an incentive to invest in building upgrades, energy efficiency, technology infrastructure and employee-focused amenities. Properties that can meet the requirements of multinational occupiers are likely to remain more competitive as leasing decisions become increasingly selective.
This shift could also strengthen the position of institutional landlords and REIT-backed portfolios, which typically have greater access to capital for redevelopment and asset enhancement.
Older Offices Face Rising Vacancy Risk
The outlook is less favourable for older Grade-B properties that cannot easily match the standards of newer buildings. As occupiers increasingly prioritise sustainable, technology-enabled and well-connected offices, ageing properties could experience longer vacancy periods and weaker rental growth.
The growing demand for IT and ITeS is another risk to watch. Any slowdown in global hiring or changes in workplace strategies among technology companies could affect overall absorption.
For developers and investors, the key question is no longer how much office space India needs, but what type of space occupiers are willing to pay for. With quality supply potentially tightening through 2028, the gap between prime and secondary assets could widen further, making location, building quality and tenant readiness critical drivers of commercial real estate performance.